Buying a Condo in 2026? Here’s What Changed with Financing
2026 Condo Loan Changes: What Can Stop You From Buying or Selling a Condo
What changed with condo loans in 2026? Starting in 2026 and 2027, condo loans require stricter HOA financial and insurance review. If an HOA does not meet reserve or insurance requirements, buyers may be denied financing, which can prevent owners from selling or refinancing their units.
Key Changes:
On March 18, 2026, Fannie Mae and Freddie Mac released coordinated updates that affect every conventional condo loan in the country. The changes cover three areas: how projects are reviewed, how much HOAs must hold in reserves, and what insurance standards now apply.
Dedicated Condo Desk. Real Expertise Behind Every Approval.
Condo financing is more complex than traditional home loans. That’s why Intercap Lending has a dedicated Condo Desk led by a Condo Desk Manager who specializes in reviewing HOA budgets, insurance, and project eligibility before issues arise.
Talk to our Condo Desk: condo@intercaplending.com
Why This Matters to You:
These changes affect buyers, sellers, and anyone looking to refinance a condo unit. A building that qualified for conventional financing last year may not qualify today. Knowing where your building stands before you make an offer can prevent a loan denial weeks into a transaction.
What do lenders now require for condo approval?
Lenders must now collect and review the full HOA package for nearly every condo project. The days of limited reviews — where a lender could skip the financial deep dive on established buildings — are over as of August 3, 2026.
- Full project review required (no more limited reviews)
- HOA budget must be submitted
- Insurance must meet updated standards
How do HOA reserve requirements affect your condo loan?
HOA reserve levels now directly determine whether a condo qualifies for conventional financing. Buildings that fall below the 15% threshold lose warrantable status, which limits buyer financing options and can affect resale value. If you’re not familiar with how HOA budgets and reserves work, our guide to HOA communities covers what buyers should look for before making an offer.
- By January 4, 2027 – HOAs must maintain 15% reserves
- Starting August 3, 2026 – HOAs without 15% reserves
- Reserve study may be required
- HOA dues may increase
- Loans may be denied
What condo projects are now easier to finance?
Not every change in 2026 made condo financing harder. Fannie Mae and Freddie Mac expanded eligibility in a few areas, giving smaller projects and established communities more flexibility than they had before.
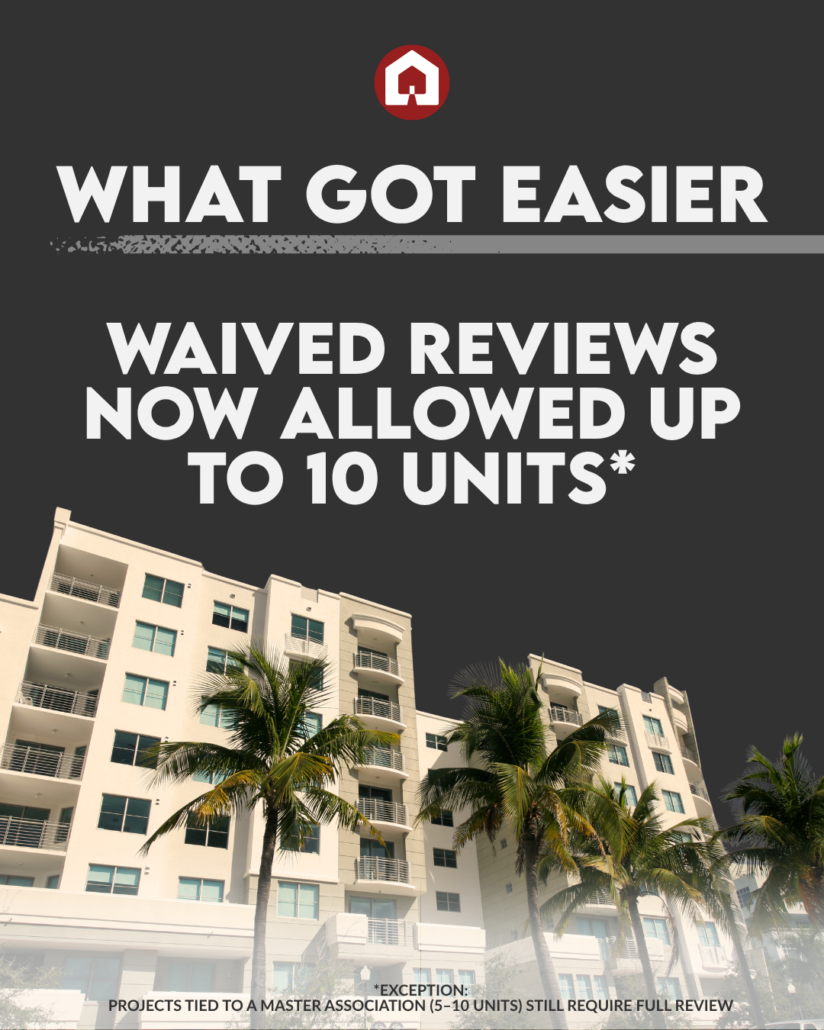
- Projects up to 10 units now eligible for waiver of project review
- Investor limits removed for established projects
- Florida Condo restrictions have been relaxed
What insurance changes impact condo loans?
Insurance requirements changed alongside the reserve and review rules. The updates set a clear ceiling on deductibles and introduced specific language requirements for replacement cost coverage — both of which affect whether a building clears underwriting.
- Effective July 1, 2026
- Replacement cost language required
- Roofs can use ACV
- Deductibles capped at $50,000
- HO-6 often required
What this means if you’re buying a condo in 2026 or 2027:
Before you make an offer on a condo this year, get answers to three questions.
- Does the HOA allocate at least 15% of its annual budget to reserves? If not, the building will lose warrantable status by January 2027. That means conventional financing disappears. Buyers are left with portfolio loans that require 20-30% down and carry rates 1-2% higher.
- Has the building completed a full project review in the last 12 months? After August 3, 2026, limited reviews are gone. If the HOA hasn’t prepared documentation for a full review, your loan approval can stall or fail at underwriting, even if you’re fully qualified. Getting pre-approved before you shop gives you a baseline, but for condos in 2026, the building itself has to qualify too.
- What is the per-unit deductible on the master insurance policy? If it exceeds $50,000 after July 1, 2026, the building is out of compliance. You’ll need individual coverage to fill the gap, adding to your monthly cost.
We can review condo HOA documents for buyers before they write offers. That single step prevents the most common financing failures in today’s market.
Frequently Asked Questions
Can I still buy a condo with these changes?
Yes, but the HOA must meet updated financial and insurance requirements.
What happens if an HOA doesn’t meet reserve requirements?
Lenders may deny financing, making units harder to sell or refinance.
Will HOA dues increase?
Possibly. Many HOAs will need to increase reserves to meet the 15% requirement.
Do these changes affect all condos?
Yes, most conventional condo loans will be impacted.
What changed for condo loans in 2026?
On March 18, 2026, Fannie Mae (Lender Letter LL-2026-03) and Freddie Mac (Bulletin 2026-C) released coordinated updates to condo project standards that affect reserve requirements, project reviews, and insurance for all conventional condo loans.
What is the condo limited review process and why is it going away?
Starting August 3, 2026, the limited review process for established condo projects is eliminated. Nearly all conventional condo loans will require a full project review, which means lenders will scrutinize the HOA’s budget, reserves, insurance, and outstanding repairs.
How much do condo HOA reserves need to be for conventional financing in 2026?
By January 4, 2027, condo associations must allocate at least 15% of their annual budgeted assessment income to reserves, up from the longstanding 10% minimum. Buildings that fall below this threshold lose warrantable status and their buyers cannot use conventional financing.
Did condo insurance requirements change under the 2026 Fannie Mae and Freddie Mac rules?
The maximum allowable per-unit deductible under a condo’s master insurance policy is now $50,000, effective July 1, 2026. However, roofs no longer need to be insured at full replacement cost, which may offset some insurance premium increases for HOAs.
What happens if my condo is non-warrantable? Can I still get a loan?
If a condo building loses warrantable status under the 2026 rules, buyers are limited to portfolio or DSCR loans that typically require 20-30% down and carry interest rates 1-2 percentage points higher than conventional financing. Learn more about non-warrantable condo financing options.