Financing Built Around Your Vision
Loan Sizes That Fit You: Projects starting around $500,000, with smaller opportunities reviewed individually.
No Maximum Limit: Your vision sets the ceiling, not our guidelines.
Simple Qualifications: Two or more years in business preferred, but strong financials or assets can qualify sooner.
Low Down Payments: Put down as little as 10% on select loans.
Smart Asset Leverage: Use existing real estate to strengthen your position and secure better terms.
Credit That Looks Beyond the Score: We look beyond the credit score to understand the full picture behind every borrower.
Ashley Siepert
Residential & Commercial Loan Officer
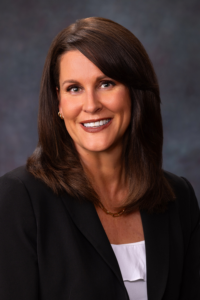
Ashley Siepert is not just a Mortgage Loan Officer; she is a seasoned professional with over two decades of invaluable experience in the mortgage industry. As a dedicated member of the Intercap Lending team, Ashley has become synonymous with reliability, expertise, and unparalleled customer service. NMLS# 91461
Mobile Number: 208-440-0637
Frequently Asked Questions
What Are Commercial Loans Used For?
Commercial loans help business owners finance growth, improve cash flow, and invest in real estate or equipment. Common uses for commercial financing include:
- Working Capital: Cover payroll, inventory, operating expenses, and short-term cash flow needs.
- Commercial Real Estate Acquisition: Purchase office buildings, retail centers, warehouses, industrial properties, or investment real estate.
- Commercial Real Estate Refinancing: Restructure existing debt with improved terms, lower payments, or access cash-out equity.
- Business Expansion: Open new locations, renovate existing facilities, hire staff, or scale operations.
- Equipment Financing: Purchase machinery, vehicles, technology, and other business-critical assets.
How Does Commercial Lending Differ From Residential Lending?
Commercial loans and residential mortgages serve different purposes and use different qualification standards.
Residential |
Commercial |
|
| Underwriting Focus | Borrower income & credit | Property cash flow |
| Key Ratio | Debt-to-Income (DTI) | Debt Service Coverage (DSCR) |
| Loan Term | 30-year fixed, fully amortized | Balloon structures, 5–10 year fixed |
| Down Payment | 0-20% | 25-35% |
| Bridge Loans | Used for gap financing between home sale and purchase. Short-term, typically 6–12 months. | Short-term (6-18 months), interest-only, higher rates. Bridges to permanent financing. |
How Long Does It Take to Close a Commercial Loan?
Most commercial loans close within 45 to 90 days after the lender receives a complete loan package.
The timeline may vary depending on:
- Property type
- Loan program
- Appraisal requirements
- Environmental reviews
- Financial documentation
- Borrower responsiveness
Providing complete documentation early in the process can help avoid delays and keep the transaction moving forward.
What are Common Commercial Loan Programs?
Business owners and investors can choose from several commercial financing solutions based on their goals, property type, and occupancy requirements.
Conventional Real Estate (CRE) Loans
Conventional CRE loans are commonly used for:
- Office buildings
- Retail centers
- Industrial properties
- Multifamily properties
Key Features:
- Typically require 25%–30% down
- Available with 5-, 7-, or 10-year fixed-rate periods
- Requires commercial real estate as collatera
SBA Loans
SBA loans provide flexible financing options for owner-occupied businesses.
Key Features:
- Up to 90% loan-to-value (LTV)
- Borrower must be a U.S. citizen
- Business must occupy the property
- Real estate collateral is not always required
Properties Typically Not Eligible:
- Multifamily investment properties
- Non-owner-occupied office, industrial, or retail properties
- Vacant land
Construction and Development Loans
Construction financing supports new development projects and property improvements.
Common Uses:
- New construction
- Land development
- Commercial build-outs
- Property expansion
Key Features:
- Owned land may be used as collateral
Commercial Bridge Loans
Bridge loans provide short-term financing when timing is critical or when a property is transitioning.
Common Uses:
- Purchasing value-add properties
- Funding renovations before refinancing
- Supporting time-sensitive purchases
- Acquiring properties before permanent financing is available
Key Features:
Rather than focusing primarily on borrower income, significant emphasis is placed on the exit strategy- how the loan will be repaid or refinanced- with typical LTV ratios ranging from 65% to 75%. These are higher cost loans, but can close quickly. Real estate is required as collateral.