SaveSmart Loan
Use your everyday cash flow to potentially reduce mortgage interest, build equity faster, and keep access to your funds.
A Smarter Way to Use Your Money
The SaveSmart Loan is a mortgage line of credit connected to a checking account that allows deposits and cash flow to help reduce your loan balance daily. Rather than keeping banking and borrowing separate, this approach is designed to help qualified borrowers use their money more efficiently.
As a result, funds that would typically sit idle in a checking account may instead work against the loan balance. Over time, this structure has the potential to reduce interest costs, although outcomes ultimately depend on deposit timing, spending habits, and overall cash flow.
Quick Facts
- A mortgage line of credit allows borrowing, repayment, and re-use of funds within a defined limit.
- In addition, the SaveSmart Loan connects this structure to a checking account so deposits help lower the balance used for interest calculations.
- Interest may be based on an average or daily balance rather than only the starting loan amount.
- Likewise, funds used for monthly expenses may temporarily reduce the balance before being spent.
- However, outcomes vary based on deposit timing, spending behavior, and overall loan usage.
A Strategy Conversation, Not a Sales Pitch
See it in Action: $1 Million Purchase
Here’s how a qualified borrower using the SaveSmart Loan compares to a traditional mortgage over time.
Assumptions:
- Estimated Home Value: $550,000
- Line Amount: $550,000
- Interest Rate: 6.75%
- Monthly Deposits: $15,000
- Monthly Spending: $8,462
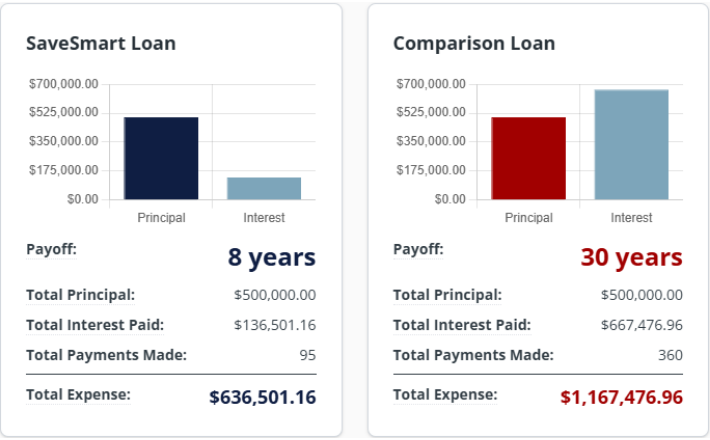
*Actual outcomes may vary based on timing of deposits, spending, draws, fees, and loan terms.
Why Homeowners Explore the SaveSmart Loan
Homeowners and homebuyers explore the SaveSmart Loan when they want more flexibility than a traditional amortizing mortgage provides.
Traditional Mortgages vs SaveSmart
Traditional Mortgage |
SaveSmart Loan | |
|---|---|---|
| Payment Structure | Fixed monthly payment | Cash-flow-driven structure |
| Banking Relationship | Separate checking account | Banking + mortgage connected |
| Interest Behavior | Interest-heavy amortization | Deposits reduce balance daily |
| Equity Access | Often requires refinance or separate equity loan | Flexible access to available equity |
| Use of Idle Cash | Idle cash sits outside the mortgage | Cash flow works against balance |
Traditional Mortgage |
SaveSmart Loan | |
|---|---|---|
| Payment Structure | Fixed monthly payment | Cash-flow-driven structure |
| Banking Relationship | Separate checking account | Banking + mortgage connected |
| Interest Behavior | Interest-heavy amortization | Deposits reduce balance daily |
| Equity Access | Often requires refinance or separate equity loan | Flexible access to available equity |
| Use of Idle Cash | Idle cash sits outside the mortgage | Cash flow works against balance |
SaveSmart Loan FAQs
What is a SaveSmart Loan?
The SaveSmart Loan is a mortgage line of credit designed to work alongside your everyday banking activity. Subsequently, rather than keeping money in a separate checking account while interest accrues, deposits into the account help reduce your loan balance and, over time, potentially lower interest costs.
How does the SaveSmart Loan work?
SaveSmart combines a home loan line of credit with a connected checking account. As income and deposits flow into the account, the available balance helps reduce the principal used to calculate daily interest. Meanwhile, borrowers continue to maintain access to funds for bills, transfers, and everyday spending.
How is the SaveSmart Loan different from a traditional mortgage?
Traditional mortgages rely on fixed monthly payments and amortization schedules, where much of the early payment goes toward interest.
By comparison, the SaveSmart Loan focuses on cash flow efficiency. As deposits are applied, the loan balance may adjust in real time, which can potentially reduce interest costs while also allowing flexible access to available funds.
What is a mortgage line of credit?
A mortgage line of credit is a home loan that allows borrowers to access available equity similarly to a revolving credit line. Instead of following a fixed repayment structure, balances may change over time based on usage. In this case, the SaveSmart Loan incorporates that structure while also integrating everyday banking functionality.
What is a sweep account mortgage?
A sweep account mortgage is a loan structure where deposits from a connected checking account automatically reduce the outstanding loan balance.
The SaveSmart Loan uses a daily sweep feature designed to help borrowers use their cash flow more efficiently.
Can a checking account help lower mortgage interest?
Potentially, yes.
Because interest is calculated daily based on the outstanding balance, deposits into the SaveSmart account may temporarily lower the balance used to calculate interest charges.
How is interest calculated on the SaveSmart Loan?
Interest is calculated daily using the outstanding loan balance. Consequently, lower balances may result in lower daily interest costs. Because deposits and withdrawals vary throughout the month, the total interest charged may fluctuate based on account activity and cash flow patterns.
Can the SaveSmart Loan help pay off a mortgage faster?
In some cases, yes.
For example, borrowers with positive monthly cash flow and disciplined financial habits, the SaveSmart Loan strategy may help reduce principal faster and lower long-term interest costs compared to traditional mortgage structures.
Results vary by borrower.
Who is the SaveSmart Loan best for?
The SaveSmart Loan works well for:
- Self-employed borrowers
- Investors
- Borrowers with strong monthly cash flow
- Financially disciplined households
- Homeowners wanting flexible access to equity
- Borrowers looking for alternatives to traditional amortized mortgages
Is the SaveSmart Loan a HELOC?
No.
Although it uses a line of credit structure, the SaveSmart Loan is designed differently from a traditional HELOC. Specifically, it integrates mortgage financing with everyday banking activity into a single strategy.
Can I still access my money?
Yes.
In other words, borrowers can continue using funds for bill payments, transfers, debit purchases, and withdrawals, subject to the available credit limit.
Can I access equity without refinancing?
One advantage of the SaveSmart Loan is that borrowers may continue accessing available equity through the line of credit structure without needing to complete a traditional refinance transaction, subject to loan terms and available credit.
Is the SaveSmart Loan a fixed-rate mortgage?
No.
Instead, the SaveSmart Loan uses a line of credit structure, which means the interest rate may adjust over time based on market conditions and loan terms.
Is there a prepayment penalty?
No. The SaveSmart Loan does not include a prepayment penalty.
Is there a balloon payment?
No. The SaveSmart Loan does not have a balloon payment.
How much equity or down payment is required?
In most cases, borrowers need at least:
- 20% down payment for purchases
- 20% equity for refinances
Additional qualification guidelines may also apply depending on the scenario.
What are the benefits of the SaveSmart Loan?
Potential benefits may include:
- Lower interest costs over time
- Faster principal reduction
- Flexible access to equity
- Simplified money management
- Cash flow optimization
- Banking and mortgage integration
Is the SaveSmart Loan right for everyone?
Not necessarily. This structure may not suit borrowers with inconsistent income, minimal positive cash flow, or a preference for long-term payment certainty. In those cases, traditional mortgage products may be a better fit.
What are the risks of a mortgage line of credit?
Because the SaveSmart Loan uses a line of credit structure, interest rates may change over time. Additionally, successful use of this strategy often requires active cash flow management. For that reason, speaking with a mortgage advisor can help determine whether the approach aligns with your goals and risk tolerance.
Are deposits FDIC insured?
Yes.
Specifically, funds held within the checking account portion are FDIC insured through the participating banking institution, subject to applicable limits.
Does the SaveSmart Loan replace financial or tax advice?
No, it does not replace professional advice.
Instead, this loan is a financial strategy and should be evaluated alongside guidance from a CPA, financial planner, or tax professional.
What does the SaveSmart Loan cost?
The SaveSmart Loan includes standard mortgage-related costs such as:
- Appraisal fees
- Title fees
- Escrow fees
- Closing costs
In addition, certain banking-related fees may apply depending on the servicing institution.
How do I know if the SaveSmart Loan fits my situation?
Ultimately, a personalized review is the best approach. A strategy conversation with an Intercap Lending mortgage advisor can help determine whether this loan aligns with your financial goals and cash flow.
*The SaveSmart Loan is subject to borrower qualification, underwriting approval, property eligibility, and program availability. Rates, terms, payments, and access to funds may vary.